For the past few years, crypto has been chasing the same dream in different forms: more yield. First, it was liquidity mining. Then DeFi farming. Then staking. Now, restaking has entered the conversation with a fresh promise that sounds almost too good to ignore: earn extra rewards by reusing the same staked capital across multiple services.
On the surface, restaking looks efficient, even elegant. Why let capital sit idle when it can secure more networks, support more applications, and generate more income at the same time? That pitch has helped restaking become one of the most discussed ideas in crypto infrastructure. It sounds like a win-win: users get added returns, networks get more economic security, and the ecosystem gets greater capital efficiency.
But the phrase ‘free yield’ is where the story becomes misleading.
In crypto, yield is rarely free. It is usually paid for with risk, complexity, or both. Restaking is no exception. In fact, it may be one of the clearest examples of how attractive returns can hide a deeper exposure layer that many people do not fully understand. The problem is not that restaking is useless. The problem is that too many people treat it like a simple yield upgrade when it is actually a stacked risk structure with new dependencies, weaker visibility, and more fragile assumptions.
The Illusion of ‘Free Yield’: Where Restaking Narratives Go Wrong
The biggest mistake people make with restaking is psychological. They hear ‘additional yield’ and immediately assume it is a bonus on top of an already productive asset. That framing is powerful because it feels efficient. Your staked ETH is already doing work, so why should it not do more work?
The answer is simple: because every extra layer of return usually introduces an extra layer of obligation.
Restaking is often marketed as a way to maximize the value of staked assets without needing new capital. That sounds attractive because it taps into a very common investor instinct: the belief that smart capital use means extracting more from the same base asset. But this framing can hide the actual structure underneath. Restaking is not just ‘more yield.’ It is a reallocation of security assumptions.
A user who sees only the reward side may overlook that the yield is paid for by taking on broader responsibility. In other words, the extra income is not free at all. It is compensation for accepting more exposure. If the underlying protocol gets more complex, if the slashing logic becomes harder to understand, or if the service being secured behaves unexpectedly, the apparent ‘bonus’ can quickly become a source of loss.
This is why the phrase ‘free yield’ is so dangerous in crypto. It invites users to focus on the upside while mentally discounting the downside. That pattern has shown up repeatedly across DeFi history. A new mechanism appears. Returns look attractive. Early users come in. Only later do they realize they were not simply earning more’they were taking on more risk in a form they had not priced correctly.
Restaking continues that pattern, but with a more subtle twist. The risk is not always obvious because it is not always immediate. Users may not feel the exposure day to day. Everything can look stable until a correlated failure, smart contract issue, or validator mistake suddenly reveals how much was hidden beneath the surface.
Stacked Risk: How Restaking Compounds Slashing and Smart Contract Exposure
In basic staking, the user delegates capital to support a network, and the main concerns are typically validator performance, slashing conditions, lockups, and protocol-level risks. Restaking expands that structure. Now the same stake may be reused to secure additional services, which means the original asset becomes embedded in a broader system of dependencies. That sounds efficient, but it also means failure can travel across layers.
Slashing is one of the clearest examples.
In staking, slashing usually penalizes validator misconduct or serious operational mistakes. In restaking, slashing risk can become more complex because it may no longer come from a single source. A validator could be exposed to conditions from multiple services. A fault in one layer might trigger penalties that affect the same underlying capital. Users are no longer dealing with one set of rules but with several overlapping ones.
Smart contract exposure adds another layer of risk.
Traditional staking already requires trust in protocol design. Restaking increases that trust requirement by introducing additional contracts, wrappers, middleware layers, and third-party dependencies. Each extra contract creates a new potential point of failure. Bugs, exploits, governance attacks, upgrade mistakes, and economic design flaws all become more relevant.
This matters because smart contract risk does not scale linearly. One extra contract is not just one extra risk. It can be a bridge into an entirely new system of dependencies. If a restaking protocol relies on multiple modules interacting correctly, then even small bugs can produce disproportionate losses. And if the system is composable, one failure can create several others.
There is also the issue of correlation.
Crypto users often think about risk as if it were isolated. They assume one protocol can fail without affecting the others. But restaking makes those walls thinner. If capital is shared across layers, then stress can spread faster. A bug in one service may reduce trust in the entire stack. A penalty in one area may affect overall economics. A token depeg, governance issue, or exploit somewhere in the chain can increase redemptions and trigger wider instability.
This is why restaking should not be viewed as a simple yield enhancement. It is better understood as leverage on security assumptions. That leverage can be useful when conditions are good. But leverage also magnifies damage when something breaks.
The important point is not that restaking is inherently bad. It is that it creates a more fragile risk profile than many users appreciate. The extra rewards are real, but so are the extra moving parts. And in systems built on code, trust, and incentives, every new layer multiplies the probability that something important gets missed.
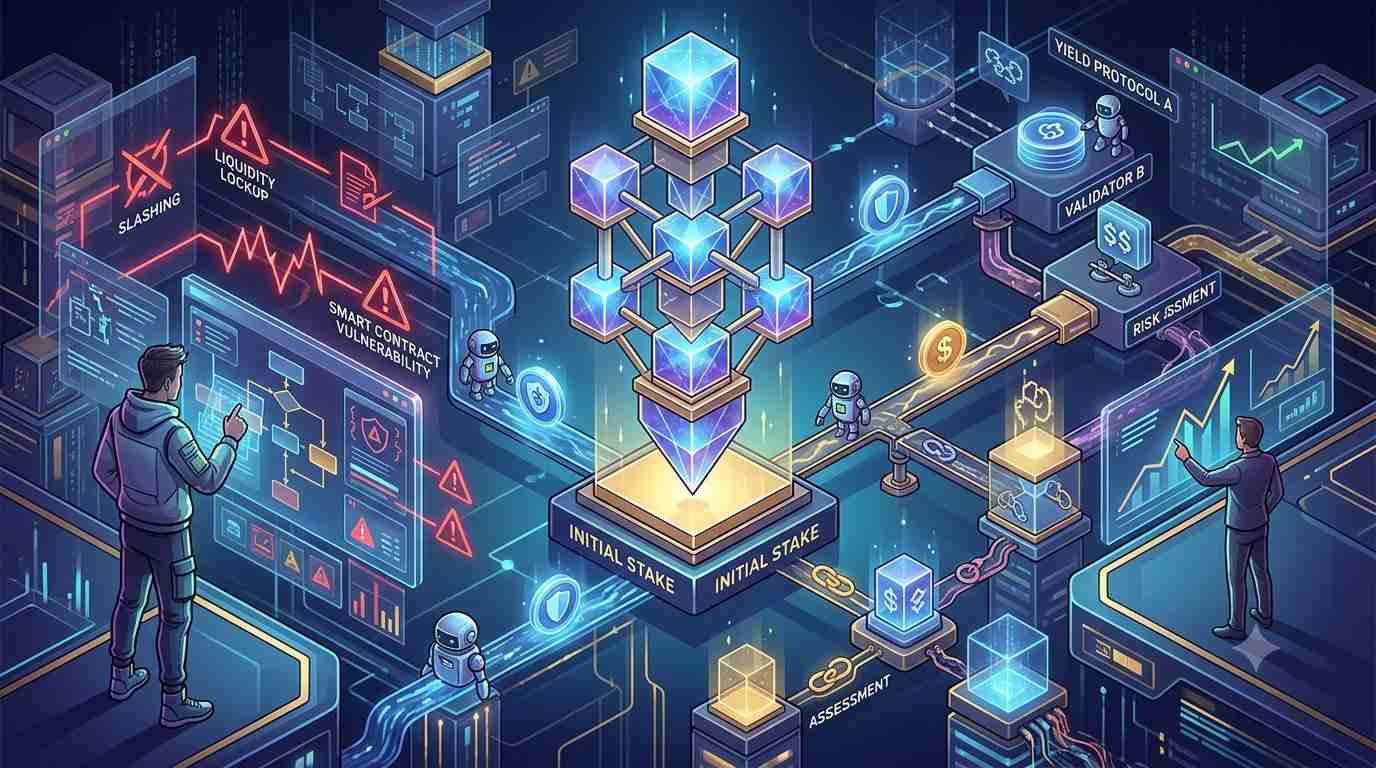
The ‘Invisible Layer’: Why Most Risk Models Ignore Restaking Dependencies
One reason restaking is so misunderstood is that many risk models were never built to analyze it properly.
Traditional crypto risk frameworks usually focus on visible, direct variables. They ask questions like: how much capital is locked, how strong is the validator set, what is the token’s volatility, how audited is the contract, and how decentralized is the network? These are useful questions, but they are not enough when the same asset is being reused across several layers of security.
Restaking introduces dependency risk, and dependency risk is harder to measure than direct protocol risk.
Imagine a protocol relying on several underlying systems that are themselves linked to other systems. On paper, each component may appear sound. But the combined structure can still be fragile because the failure of one layer can ripple through the rest. This is the invisible layer most models miss. The issue is not just whether each contract is safe on its own. It is whether the relationships between those contracts are stable under pressure.
That is a much harder question.
A standard model may tell you that Protocol A has a strong audit and Protocol B has good incentives. The risk is not distributed as widely as it appears. Instead, it may be concentrated in the same source of capital and the same operational base.
This is where restaking becomes especially difficult to model.
The issue is not just technical complexity. It is also epistemic complexity, meaning we do not always know what we do not know. Some dependencies are documented. Others are hidden in code paths, governance assumptions, or behavioral incentives. A risk dashboard may show healthy metrics while missing the deeper structural connections that actually determine resilience.
Another reason models fail is that they often assume normal conditions.
Under normal conditions, restaking may look stable. Rewards flow. Validators perform. Users feel comfortable. But risk models are tested under stress, not calm. The real question is what happens during adverse events: market panic, correlated withdrawals, governance disputes, software bugs, or slashing incidents. Those are the moments when hidden dependencies become visible.
At that point, users discover that the system is not just a collection of independent contracts. It is a web. And webs behave differently from isolated assets.
There is also a human bias involved. Yield can blind people to complexity. When returns look good, users become more tolerant of opacity. They assume that if the market is rewarding the strategy, then the strategy must be acceptable. But in crypto, that assumption has repeatedly been proven dangerous. High yield often means the market is pricing in something users have not fully understood yet.
In many ways, restaking is a test of whether the market can learn to price complexity honestly. So far, the evidence suggests that it is still early.
Liquidity, Exit Risks, and the Myth of Instant Unwinding
One of the most comforting beliefs in crypto is that positions can be exited quickly.
This is partly true in liquid markets, but restaking complicates that assumption. Users often assume they can unwind positions whenever they want, yet the actual exit path may be slower, more expensive, or more constrained than expected. Once capital is tied into a restaking structure, leaving is not always as clean as entering.
The first issue is time.
Some staking and restaking mechanisms involve withdrawal delays, unbonding periods, or protocol-specific queues. That means capital may not be instantly available during a market downturn. If a user wants to reduce exposure because conditions are worsening, the system may not allow immediate exit. That mismatch between market speed and protocol speed is one of the quietest but most important risks in the entire structure.
The second issue is liquidity fragmentation.
Restaking positions may not always be easy to transfer, hedge, or unwind efficiently. In principle, liquid staking or derivative wrappers can improve flexibility, but they also introduce their own dependencies. Liquidity may exist, but not at the exact moment it is needed, or not at the price the user expects. In stressed markets, that gap can widen dramatically.
The third issue is reflexivity.
If many users try to exit at once, the very act of unwinding can make conditions worse. Liquidity dries up. Secondary market prices fall. Wrapper assets trade at discounts. Validator economics get strained. What looked like a stable earning strategy can suddenly become a crowded trade with poor escape routes.
This is particularly dangerous because restaking users may underestimate the difference between paper liquidity and real liquidity. Just because an asset has a market price does not mean it can be sold without impact. Just because a protocol claims flexibility does not mean that flexibility holds during stress. And just because a position is technically withdrawable does not mean it is practically unwound in a useful timeframe.
Conclusion
Restaking is one of the most interesting ideas in crypto because it promises efficiency, composability, and additional yield from already deployed capital. That promise is real, but it is incomplete. The phrase ‘free yield’ hides the fact that every extra return in this system is paired with extra responsibility, extra dependencies, and extra exposure.
The illusion begins with the narrative. Restaking sounds like a bonus layer, but it is really a risk layer. It compounds slashing exposure, expands smart contract risk, and creates interconnected failure paths that are easy to underestimate. It also introduces an invisible dependency web that most traditional risk models do not fully capture. On top of that, liquidity and exit mechanics can make the system far less flexible than users assume.
Taken together, these issues point to a simple truth: restaking is not free money. It is a trade-off. It can be useful, but only when people understand what they are giving up in exchange for the yield they are chasing.
That is the real lesson. The future of restaking will not be decided by how attractive the rewards look in a bull market. It will be decided by whether the ecosystem can honestly model the risks that come with them. Until then, the smartest approach is not to ask how much extra yield restaking can produce, but what hidden cost that yield is quietly paying for.